Wednesday, March 08, 2006

Success is just a tweak away

How fine is the line between success and failure? So small that sometimes it’s measured in seconds.

Here’s how one business found success through a teeny-tiny policy change that made all the difference.

In the 1950s, the National Basketball Association was in trouble. As soon as one team got a healthy lead, players would “freeze” the ball, passing it around aimlessly or dribbling the ball in their own end till they were fouled. The lack of offence was killing the game just when it was struggling to be recognized as a big-league sport.

According to a story, 24-Second Clock Revived the Game, at http://www.nba.com, the owners realized something had to be done. Looking at baseball, with its three-strikes-you’re-out rule, and football with its "downs", the owners realized that they needed to introduce more time pressure into the game.

Result: the shotclock, which forces a team to advance and shoot within 24 seconds – or takes the ball away from them. In its first year, the 24-second rule boosted each team’s average score by 13 points – and ensured more baskets were scored from offense than the foul line.

Declared Danny Biasone, late owner of the Syracuse Nationals: “Pro basketball would not have survived without a clock.”

I believe business failure is never inevitable – and success comes only from constant tweaks, innovations and adjustments. What changes could you make in your business to restore the original passion and excitement – and help your company reach its full potential?

I bet it’s there. I bet it’s simple. And I bet it’ll work.

Today the 29 NBA teams are worth nearly $10 billion.
What’s preventing your business from becoming a superstar?

Monday, March 06, 2006

Executive Blogging

I just got back from a lunch downtown featuring two icons of contemporary business blogging: California-based blogger/author Shel Israel, and Waterloo, Ont-based Synnex Canada CEO Jim Estill.

Since I was there on assignment for PROFIT-Xtra, you'll have to wait to read my take. But nothing should stop you from clicking on this post from Ottawa PR guy Joe Thornley, a student of the new conversational media.

He'd make a pretty fair journalist (if he could take the pay cut).

Me, I was surprised how few people were there: 25-30 in a room that holds a hundred. While Shel Israel is out there evangelizing about business blogging, the mainstream business community seems to be taking a pass.

Could be they're still looking for the ROI. Which they won't find by sitting on their duffs.

(Do you know a successful -- okay, we'll settle for readable -- business blogger here in Canada? Let us know by leaving a comment. Or send me an email at rick (at) rickspence.ca)

Friday, March 03, 2006

5 Simple Strategies to Boost Your Advertising Results

"StreetSmart Marketer" Michael Hepworth really is a smart guy.

In his latest newsletter, he kind of blogs about his experience creating his first single-purpose website - and how much more effective it seems to be than the "all things to all people" website he's been using. It's a personal tale with great resonance. Check it out here.

In the same issue, Michael offers "5 Simple Strategies to Boost Your Advertising Results," and they're so useful I thought I would reprint them (with permission) here.

1. Up-front, you need your prospects' undivided attention. The only way you can do this is with a strong headline that speaks to their dreams, desires, frustrations, and fears. Your headline offers the reader a bribe, in the form of a strong benefit, in return for reading your advertisement.

2. Unless you can convince them to read your entire message, you will produce poor results. Encourage readers to devour your whole message by showing them how you will bring value to their lives if they'll just give you a few minutes. You must then deliver that value in your sales message.

3. Offer immediate proof of your claim before you get into your message. Testimonials are one of the most valuable but undervalued ways of convincing prospects that you can meet their needs and, fulfill their dreams and desires or remove their frustrations or fears.

4. Everyone wants a bargain. You have to show them how much value you bring. You must convince your prospects that what they spend with you is minimal compared to the benefits they’ll receive.

5. Make it easy to buy from you. Everyone is secretly asking to be led, so tell your prospects exactly what action to take to buy from you and show them how easy it is to order.

Use these as a checklist for every piece of direct mail and for every advertisement. Do them consistently and above all do them compellingly, and watch your response rates soar!

You can read more about Michael and his business here.

Wednesday, March 01, 2006

Discuss

"There is no such thing as a good off-strategy idea."

Randy Pilon, founder and CEO, Virox Technologies Inc.
- as quoted by David Woolford, Virox chair, in a presentation Feb. 7 to the Ontario Centres of Excellence Discovery 2006 conference.

Success is all about focus, right?

I agree with Randy. But how then do we categorize serendipitous discoveries, such as new markets or Post-It Notes?

In real life, I think the truth is, "There is hardly ever a good off-strategy idea."

But Randy's remark is catchier. And it makes the point: Success is much more likely to come from disciplined focus than from chasing every opportunity that comes along.

Tuesday, February 28, 2006

Victoria's Secrets

“Ladies Who Launch” is a website for women business owners founded by Cleveland-area entrepreneurs Victoria Colligan and Beth Schoenfeldt. The company describes itself as providing “content and community to help women start and expand their businesses and creative ventures.”

I’m not sure what that means, but I do like the list of Top 10 Business Tips written by co-founder Victoria Colligan. She may be a former lawyer, but she clearly knows that entrepreneurship is a mind game - and you can train yourself to win.

Rather than steal all of Victoria's secrets, I’ll share with you my five favourites. You can click through for more if you like.

1. Train yourself to discern quality in everything you do and in everyone you choose to work with. Do not settle for mediocrity. You always have options.

2 Make the phone call you dread the most first. Make one hard phone call every day towards your goal.

3. Use negative and positive feedback to clarify your business message. View negativity as an opportunity to evolve.

4. Take at least 3 action steps every day towards your final goal.

5. Pay attention to signs that may indicate a change in direction. Your venture will evolve. Your ability to adapt is important.

So many people claim they want to be successful. They say they want to build their business. Well, Victoria's handing you the tools to do both. In five easy steps.

Click here for all of Victoria Colligan’s 10 tips. Or go here for more on Ladies who Launch.
Or just start working on quality, courage and action.

Another Blog Milestone!


It’s time to celebrate: today Canadian Entrepreneur welcomes its 4,000th visitor!

This blog is still small potatoes (at current traffic rates, it’ll take eight years for the accumulated readership of this blog to equal the readership of one of my columns in PROFIT or MoneySense). But this is a more specialized, interactive and fun way to communicate, and I thank you for your participation.

We’re also still on a growth curve. It took seven months to get our first 1,000 visitors. Our next 1,000 took 100 days. The next thousand took 64 days. We gained our most recent thousand in 38 days. So the sky is still the limit.

Feel free to subscribe to this blog, bookmark it, link to it or forward to your friends. Gotta keep the momentum going somehow.

Monday, February 27, 2006

The Ultimate Question

Last week I started reading this fabulous book from Fred Reichheld, a customer-loyalty guru in Boston, called The Ultimate Question: Driving Good Profits and True Growth. It is officially being published next month. While this book is aimed at corporate executives, it underlines the importance of having a strong customer focus.

Reichheld says too many companies are dependent on “bad profits” – revenue from tactics that alienate customers, such as charging service charges and monopoly premiums or cutting back on service. He says that companies grow much faster and more sustainably when they focus on “good profits” – revenues that accrue from customer-pleasing strategies, such as offering lower prices (e.g. Southwest Airlines) or creating better customer experiences (think Amazon.com) or building community (think eBay).

He and his colleagues at Bain & Co. did a multi-year customer loyalty study that found that companies that increase customer retention by 5% can yield a 25% to 100% increase in profits. The problem is, most employees are measured and compensated not on retention or customer satisfaction, but on sales and profits – metrics that do not distinguish between what’s “good” or “bad” for customers. Thus, many executives take the easy way out and compromise the customer experience in order to make their numbers.

Here’s how you make this work for you.

1. Ask customers this simple question:
How likely is it that you would recommend this company to a friend or colleague?

2. Based on the responses to this question, calculate your Net Promoter Score. (Subtract the number of customers who are Promoters of the company from the number who are Detractors.) Reichheld’s research has found that companies with the highest percentage of promoters enjoy strong profits and healthy growth.

3. Continually monitor your NPS and include those results in all calculations of executive compensation or bonuses. That which is measured (and rewarded) gets done.

Run (don’t walk) to your bookstore. This is an easy to read book with a powerful message.

Or, download Chapter 1 for free by clicking here. (Ain't the Internet grand?)

Thursday, February 23, 2006

The Long Tale: CEO Succession

Here’s an interesting case study of the power of blogging. And it started right here…

Noam Wasserman, a professor at the Harvard Business School, writes an article on CEO succession. I blog about it. Jim Estill of Synnex Canada, a CEO who reads this blog once in a while, leaves a comment about how he handled his evolution from founder to CEO of a $1-billion company.

In Boston, Wasserman finds my blog and mentions it in his blog, Founder Frustrations. He pays special attention to Jim’s comment, since that’s first-hand experience (or primary research, in academic jargon). I saw his post, noted his dissatisfaction with Jim’s answer below, and emailed Jim to let him know.

The result: Jim visits Wasserman’s blog, leaves a comment about how he’s not done yet – his goal is to run a $10-billion company – and then posts more on his own blog about the challenges he’s overcoming as a CEO who needs to keep growing personally even faster than his company.

So there it is: real-time business education, for professors, CEOs and the rest of us, all thanks to the miracle of blogging.

To see Wasserman’s post, along with Jim’s comment, click here.

To read Jim’s new post on "CEO Success - Transitioning from Founder to CEO," click here.

Here are Jim’s main points on successful transitioning (for those who would rather not chase this thread any further):

1 - As always, I need to think bigger.

2 - I need to refine my time systems to handle increased volume.

3 - I need to get other people to make decisions. Organizations fail if every decision needs to be done by one person.

4 - I need to seriously consider where I might add the greatest value and leave areas where the value I could add was low

5 - I need to figure out and address the needs of all my bosses - the customers, the vendors, the staff, head office, etc.

7 - To grow, I needed to give things up.

8 - Larger companies need more replicability. This means good processes that can be repeated. This can be tough on entrepreneurial spirit. But again, if the idea is big enough, then I take the challenge to come up with a process.

Wednesday, February 22, 2006

Thinking before speaking

Today Paul Litwack, who calls himself “the Capability Improvement Coach,” asked readers of his newsletter to contribute ideas on how to “tame the tongue.”

“Words can be powerful,” he says, “and I too sometimes treat them like they are free.”

I believe some of the trickiest communication problems take place when you are in a position to criticize others. In my experience, many people in the role of mentor or advisor avoid such conversations, since the results can be so unpredictable – and sometimes messy. To shun such opportunities, however, is to abdicate your responsibility to your protégés, clients or colleagues.

So here is the advice I e-mailed Paul.

When working toward a criticism or critique, whether it be an employee, client or colleague, I speak slowly and carefully. I establish the difficulty of completing this specific task successfully, to reduce any sense of failure or shame on the part of the person who is sub-performing. I will often talk about a time when I made a similar mistake. (Fortunately, there are lots of those.)

Before I start talking about remedies and strategies for improvement, I like to get the person talking about what they think they could do better.

If you don't do all this in your role as mentor, you run the risk of having the other person focus on one thing: their mistake. Their failure. They may even start internally to question their ability to do the job. They certainly won't be listening to whatever you're saying next -- which is why you need to get them talking and focusing on moving forward.

In business today, not enough bosses/colleagues/consultants have the chutzpah to confront and correct. And most of those who do focus too much on the negative. Yet when done properly and constructively, criticism can be a precious gift.

How do you tame your tongue?

Tuesday, February 21, 2006

Win or Lose, it's all the same


Congrats to the Canadian Women's hockey team in Torino, winners of Olympic gold!

A friend passed on this insight from sports psychologist Peter Jensen, who works with the Canadian women's team. In hockey, says Jensen, motivation is simple:

"It's, 'If we win, let's go for a beer. If we lose, let's go for a beer.'"

Next time HR tries to overcomplicate things, keep this in mind.

Thanks to Jeff for this one.

Simon Cowell: "So many unhappy billionaires"

Business Week Online recently did a fun Q&A with Simon Cowell, acid-tongued star of American Idol.

What has this got to do with entrepreneurship? It turns out the celebrity judge is a serial entrepreneur. After starting in the music biz in London with giant EMI Music Publishing, he went on to form several record labels as well as a TV production company.

In March, his next competition show, American Inventor, will debut on ABC. Fledgling entrepreneurs from across America will compete to come up with the best new product.

Here are snips from his interview with BW's Stacy Perman.

You're best known as the tough judge on American Idol, but do you consider yourself a music man or an entrepreneur?
An entrepreneur. I've always treated the music business as a business. Whether I'm making TV shows or signing artists, you have to do it by the head and not the heart -- and I run my businesses that way.…

Do you find a difference in entrepreneurialism in America and Britain?I think America is a hard nut to crack. But once you get a toehold it's a great place for an entrepreneur because people are so enthusiastic...

What would you consider essential to being a successful entrepreneur? Work hard, be patient, and be a sponge while learning your business. Learn how to take criticism. Follow your gut instincts and don't compromise.

What role has failure played in you career? For instance, your label Fanfare Records went under in 1989, and your reality show Cupid was canceled in 2003.
When I was 30 the company that owned Fanfare went bust, and I effectively lost everything. I had to move in with my parents. In hindsight, it was the best thing that happened in my life because I learned the value of money: not to borrow money and not to live beyond my means. And I learned that getting there is more fun than being there. But one thing that I have always been able to do is to own up to my mistakes and not blame others.

As for Cupid, we compromised. We allowed other people to make decisions for us, [but] I don't blame anybody but myself for allowing that to happen.…

Who have been your role models?
I actually really like Donald Trump. I think he's entertaining. There are so many unhappy billionaires, and he's a happy one with a great sense of humor. I didn't think I'd like him. I like people [who] don't take themselves too seriously.

Idol music lovers may read the whole story here.

Friday, February 17, 2006

Your Guide to Business Capital


PROFIT Magazine has just published its 2006 Finance Guide, an epic article I worked on most of last month.

If you're looking to raise funds for your business, this story looks at hot new financing sources and reviews the state of the art in Angel investors, Asset-based lending, Private equity, Venture capital, Public venture capital, Venture debt and ordinary commercial banking.

For those too busy to click, here's an excerpt.

Across Canada, moonlighting entrepreneurs, semi-retired executives and other venturesome high-net-worth individuals are looking to invest in private, early-stage businesses with great growth prospects. They come in earlier than the venture-capital funds, consider relationships to be as important as the business plan, focus less on high-tech businesses than most VCs and invest anywhere from $20,000 to $500,000.

Some angels are mainly after higher returns than they can get from indexed mutual finds. But many others are motivated by the thrill of being involved in a risky, growing business that needs both their expertise and cash. They tend to enter the picture after a firm has burned through its "love money" (from "friends, family and fools"), and well before it can earn the attention of VC funds. They hope to hang in for three to five years, then collect a big payout as the firm starts making hay in its market or attracts venture capital.

(SNIP) .... Where angels used to keep a low profile to discourage endless appeals for money, today more and more of them are uniting in "angel networks" to systematize the vetting of potential deals and share the risk with fellow angels. Sean Wise, president of Toronto-based Wise Mentor Capital and a close observer of the equity scene, says this reflects a new mentality: "Before the tech bubble, they were very much more lone wolves, investing in one company at a time. Now they have banded together to share best practices, increase their bandwidth, work together on due diligence and boost deal flow."


(SNIP)...But you don't have to go through formal organizations to find an angel. They're all around: a recent U.S. study shows 3% of Canadians invest in private businesses. And most aren't joiners.

Andrew Patricio, a partner in Toronto-based Biz Launch, says many of his clients are accessing relatively large sums from non-aligned angels. Local angels invest after a lot less due diligence than regular VCs, and are generally more open to investing in a variety of sectors. Patricio says he knows one entrepreneur who just scored $500,000 to make fishing rods, and a makeup distributor who raised $250,000.

Don't stop now! You can read the whole story here.

PROFIT's Jim McElgunn, my assigning editor on the project, also offers a good interview with consultant Sean Wise on "Five Keys to Getting Cash." Click here for more.

Is it just me?

I have noted for a while that it seems to be getting harder and harder to get people to call you back or respond to an e-mail.

This has always been an issue for sales people, but my experience used to be that most people would return calls fairly faithfully if they it didn’t require them to pull out their wallet.

Over the past week or so I have had occasion to make a lot of calls to individual business people, some of whom I knew or have met before, some of whom I don’t know at all. My response rate is only about 30%.

Clearly this is my fault for not providing a compelling enough message. On the other hand, I didn’t think it would be necessary. Yes, I am trying to get these people to participate in something, but I thought the benefit to them was pretty obvious.

So there's a lesson in itself. If you want people to return your calls, give them a compelling reason why it’s in their interests to do so. Don't assume they’ll take the time to think it through and recognize the benefits on their own.

But why are callbacks and return e-mails so hard? After all, we’re in the era of “instant-on,” where everyone carries their phones everywhere and checks email obsessively.

My theory is that instant e-mail has reduced our attention spans. We now respond readily to urgent messages that require very little thinking. But if a message requires a little more judgment and reflection, I suspect we put that off. With the sheer volume of calls and e-mails we all get, perhaps a message that has been read once but not responded to falls quickly off the to-do list – just as it literally scrolls right off the monitor screen as new messages pile up.

Since I believe that business is a subtle art form that demands thinking and reflection time, this scenario scares me just a little.

Maybe you have another theory as to why it’s so hard to get messages returned? Please share it here by clicking on comments, below. The best response will win a prize. (See? I’m learning.)

Thursday, February 16, 2006

Affordable PR for Smart Businesses

How do you get the PR you need? You select your target media and then write articles that they want to run.

Well, it’s a little more complex than that, but not by much. As a content marketing specialist, I believe many companies are missing the boat by not submitting more articles to the media on appropriate issues that would interest (and impress) their customers and prospects.

Earlier this week I spoke on article writing at my local chapter meeting of the Canadian Association of Professional Speakers. I also handed out a one-page tipsheet, “Key Elements of Article Writing,” featuring story ideas, media suggestions and guidelines for better writing.

The handout is a little too long to reprint in this blog, but if you’re interested in the subject, I’d be happy to send you a free copy. (It's just a one-page Word document, nothing fancy.)

Just e-mail me at rick(at)rickspence.ca and put “article handout” in the subject line. (Use the @ instead of the “(at)”, of course.)
(If you also want to add a comment on this blog, I’d be happy to receive your feedback.)

Here’s a quick sample from the handout to whet your appetite.

Questions to ask yourself:
1. Who is my market? Who am I trying to reach with my writing?
2. What media (newspapers, Internet, magazines, radio, podcasts, etc.) best help me reach my market?
3. What kind of content are the editors of those media looking for? How can I pass their screen?

It’s just a primer. But if you have any questions after reading the handout, leave a comment here, and I will respond as best as I can.

Now get writing!

Tuesday, February 14, 2006

The strange politics of CEO succession

Should the founding entrepreneur stay or go?

I found an interesting article this week from Harvard’s Arthur Rock Center for Entrepreneurship. It’s about the strange politics of CEO succession that often results when a small business becomes so successful that the person who founded it can't run it properly any more.

There are always exceptions to this phenomenon – look at Bill Gates and Larry Ellison, or, closer to home, Frank Stronach or Jim Estill (click here for the blog of a CEO who loves to learn). Generally, however, most entrepreneurs aren't the right people to manage large, complex businesses. We all have our limits.

Professor Noam Wasserman of Harvard Business School’s Entrepreneurial Management Unit has studied what he calls founder frustrations. Here’s the paradox he sees:

“In large companies, when the CEO doesn't do well, the CEO gets replaced. When the CEO does do well, there is almost no chance that person will be replaced…

"My research shows that in small companies, it's still true that when founder-CEOs do badly, they are replaced. But the interesting paradox is that when founder-CEOs do really well, that also increases the chances that they're going to be replaced.

“The challenges within the company change so dramatically that the person who was best suited to lead the early stage of company development is no longer the best person to continue leading the company. Now, the product has to be sold: You have to create a sales organization, manage multiple functions, deal with customers, handle more complex financial issues, and deal with a very different set of challenges for which many founder-CEOs are not equipped.”

The trouble is, convincing the founder it’s time to go. “Objectively, many founders might agree that the CEO's job will require skills they don't have, but emotionally, they are very attached to the companies they started.”

Wasserman notes the pattern is even more pronounced when outside investors are involved. “VCs, in particular, often make the assumption that the person who started the company is going to have to be replaced along the way, and may therefore have a quicker ‘trigger finger’ than the founder-CEO wants.”

But all is not lost. While ex-CEOs in big business usually make a clean break, that’s not necessarily so in smaller businesses. “In entrepreneurial companies, the board often tries to find ways the founder can remain within the company in a different role, such as remaining on the board or taking a lower-ranking executive role. Because those founders are so central to their companies, losing them completely could be very disruptive for the company. The ideal situation is where the board and the founder can craft an appropriate non-CEO role, one that the founder willingly takes on.”

Of course, such changes do not come easy, Wasserman warns. “Given how hard it is to convince many founders that they should step down, there is also a big cost to keeping a disgruntled founder active in the company.” Stepping in to run a company is never easy, he notes, “but doing it in that kind of situation brings the challenge to a very different level.”

Read more here.

And Jim Estill, if you're reading this, why do you think you've been an exception?

4 pm UPDATE: Jim, the CEO of Synnex Canada, a $1-billion distributor of technology products that began out of the back of his car, has responded to the question! Check out his answer under "Comments," below.
And feel free to leave your own.

Thursday, February 09, 2006

Your Belated Birthday Present

When I celebrated this blog's first birthday last week, I had hoped to inaugurate a new feature: the "Most Popular Posts" archive. I created it to help you find the more popular or significant posts from among the more than 200 Canadian Entrepreneur posts now cluttering up cyberspace.

Unfortunately, I messed up the code, so it wasn't ready in time for the official birthday. So consider this a belated present to you.

To find my most worthwhile posts, scroll down the right side; the new archive starts right after the list of "Best Links."

Lessons from Canada's emerging growth companies


I’m just back from a presentation at the National Club in downtown Toronto, where I spoke to a group called Future Leaders on "Lessons from Canada’s Newest Growth Companies." Using information derived from PROFIT Magazine and from my own journalism for the magazine, I analyzed some of the top companies on the PROFIT 100 list of Canada’s Fastest-Growing Companies, and shared a few of their common business strategies and favourite success tactics.

Here are a couple of excerpts, and a few personal comments (in italics).

“These are trying times for entrepreneurs. We’ve had several years of strong economic growth and stock market growth – the usual indicators of prosperity – but a lot of businesses aren't seeing any of it. We’re trying to compete in a world economy with rising energy prices, high commodity prices, a high dollar, and increasing competition from China and other countries for our manufactured goods – and, increasingly, business services.”

(Little did I know that there were several entrepreneurs in the audience who are actually engaged in outsourcing business services to India. I met two of them after my speech. Which serves to remind us that one business’s problem is always another’s opportunity.)

"It takes a lot of confidence to survive in business today. You’ve got to have the optimism of a 10-year-old hockey player, who knows that the game does not always go to the strongest or the swiftest, but to the team that wants to win the most. But wanting to win doesn’t mean trusting to pluck and luck.

"It means working hard, preparing yourself and your team to go out and win. And you do that by fine-tuning the ways you manage your business, transforming your staff into an aligned, effective and close-knit team, elevating your relationships with customers, suppliers and other stakeholders, and constantly looking ahead to see how you and your products and services can add more value.

"These are, of course, truisms. But they are nonetheless true. People who own their own businesses or manage business units have remarkable power at their disposal. Because every business can be improved, every process and policy you have can be rethought, and every business relationship you have can be made stronger….

"What I want to do tonight is share some of the strategies and tactics that have fuelled the success of Canada’s fastest-growing companies….

(I then profiled the top 5 companies on the list, whom I interviewed last year. Then I tried to point out some of the commonalities that unite these diverse businesses.)

First, these companies were all founded on innovation. They present new solutions to their markets, not business as usual. Angiotech jump-started a new line of medical research and a whole new industry. Pethealth broadened the market for a niche product by selling pet insurance through retailers, animal shelters and the Net. Fundtrade offered financial planners a better way to do business. These firms have written the book on innovation – yet they demonstrate how innovation is just as much a product of our imaginations as it is of the high-tech laboratory.

Second, these companies offer real value. Pethealth entered the market charging less than its competitors. Glacier Ventures helps media owners sell out and yet keep a stake in the future growth of the organizations they owned – upside potential that keeps them engaged and performing. Hostopia puts its clients in a new, high-tech business, and lets them keep most of the profits. If your firm wants to deal with growth firms like these, keep in mind that they will be most receptive to suppliers who also put value first.

(Then I offered seven proven success tactics of these companies. Here’s my favorite.)

"No. 6: Successful growth companies communicate all the time. They have to: things move so fast that if they don't keep everyone in the loop, sales, morale and customers all can suffer.

"When PROFIT’s No. 1 company, Hostopia, was facing hard times in September 2000, founder Franc Nemanic called a staff meeting and explained that Hostopia had to sign up 100 new websites a day by the end of the year — a fourfold increase. "A sense of urgency motivates the whole organization," says Nemanic. "We told them where we were and what we had to accomplish to survive. It made them realize we were all going to sink or swim as a team."

Nemanic kept his team paddling by providing a daily report on Hostopia's progress toward its target. "It was a continuous process of communication." He says even non-sales staff adopted the mission, with administrators and programmers focusing their efforts on helping sales. "As long as you have a customer-centric attitude and you're focused on helping other people achieve their goals," says Nemanic, 'everyone will achieve their goal.'"

Also on the program, and speaking (thank goodness) after me, was Manjit Minhas, owner of Minhas Creek, a $40-million-a-year Calgary-based distributor of low-priced beers sold in Manitoba and Saskatchewan. She has been trying for two years to break into the Ontario market. She is headstrong, dynamic and very well spoken. She is 25 years old.

Believe me, you wouldn’t have wanted to speak after her, either.

Tuesday, February 07, 2006

Ten Steps to a Business Turnaround

I haven’t had the time yet to report on the “Comebacks that Last” conference held at the U of T's Rotman School last week. There were some quite revealing presentations, but even those that were less than forthcoming still contained worthy insights. (Did you know that Ronald McDonald got a wardrobe makeover?)

The point was to learn from businesses that had been “to a dark place” and tried, in an orderly and strategic way, to come back. Among those businesses: TD Bank, the Hamilton Tiger Cats, Canadian Tire, the Art Gallery of Ontario, McDonald’s, Maclean’s Magazine, and others.

I’ll blog later on some of the individual presentations, but the overall lesson was this: coming back from the dark place takes courage, commitment and knowledge.

Here’s a rough draft of the Ten Steps in a Successful Turnaround:

1. Acknowledge the problem.

2. Find a new management perspective (i.e., the people who got you into the problem are rarely the ones who can get you out).

3. Measure the problem. (You need the "before" metrics so you can set some goals.)

4. Study the problem. (Include customers and employees in your research, as well as standard sales and production metrics.) Understand what’s not working.

5. Build awareness of the problem and a commitment to change.

6. Come up with a bold plan that incorporates new goals, new targets, new customer benefits and new ways of doing business.

7. Create buy-in for your plan inside and outside your organization.

8. Don’t be afraid to demand bold change (e.g., some top performers at TD had to accept a new system of compensation). Without attitudinal and behavioural change, your new new plan will not work.

9. Segment your objectives. Celebrate each success. Reward change.

10. Be ready to do it again, because comebacks never last. Dark times are part of the business cycle.

Which is why turnaround management matters so much.

Thursday, February 02, 2006

The Mysterious Island

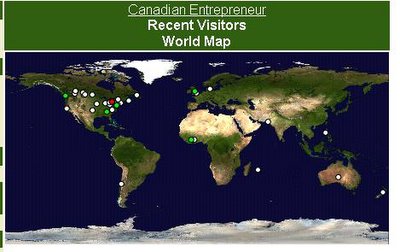
I've had a couple of inquiries about the map below - specifically, about that little dot in the middle of the Indian Ocean. Some castaway in a lifeboat surfing with his Blackberry, perhaps?

Nothing quite so romantic. That visitor came to us from the wonderful island nation of Mauritius, a blend of Creole and East Indian cultures with a French accent and a flourishing economy based on tourism, sugar cane and finance. (A friend of mine lived there back in the '80s while her husband was on assignment for the World Bank.)

As of 1 am tomorrow morning, it was 27 degrees C in Mauritius. A perfect place to be this time of year.

Happy Birthday, Blog!

This blog is one year old today!

Here are the stats: 3,228 visitors, 5,666 page views, and 250 posts. Plus, this site has enabled me to sound off with some ideas, share best practices from other Canadian entrepreneurs, meet new people, and celebrate the richness of entrepreneurship in this country.

What I’m proudest of, however, is reaching an international market – not just for my writing, but for Canadian entrepreneurs as a whole. This blog is being read by people all over the world, and it’s a chance to show what cutting-edge products, people and ideas are coming out of the Great White North.

Here’s a map of 100 recent visitors to this site – as you can see, they come from every continent – though Canadians are, of course, best represented.


Thanks for your participation. It’s been a great year!

Wednesday, February 01, 2006

Comebacks that Last

Here’s your heads-up on a new conference coming up Feb. 3 from the innovative minds at Rotman, the University of Toronto’s business school.

“REBOUND: STAGING A COMEBACK THAT LASTS” will look at great comebacks in the worlds of business, arts, media and sports.

I have always believed you can learn more from turnarounds than from unalloyed success stories. “Comebacks” allow you to study much more typical, flawed organizations. You see how they reassessed their situation and their strategy, and learn how they built things back up again. It’s much more relevant to most organizations than simply, “We had a good idea and a good team and things took off.”

(BTW, the best business comeback story I ever heard was from a non-profit organization. Elyse Allan, now president of GE Canada, does a wonderful presentation on how she had to turn things around under pressure soon after becoming president of the Toronto Board of Trade. She had to lop operations, change the culture, even sell the art on the walls. It’s an inspiring story you should ask her about sometime.)

She’s not on the roster at Rotman on Feb. 3, but McDonald’s, TD Bank, Canadian Tire and Maclean’s Magazine are. As well as Bob Young, owner of the Hamilton Tiger-Cats, and presenters from the Royal Ontario Museum and the Art Gallery of Ontario.

Learn what it takes “to face up to the unique challenges of a turnaround situation and craft a new strategy for lasting success.”

You can get more details or register at http://www.rotman.utoronto.ca/businessconference/

In case you can’t make it, I will try to get down there for at least Friday morning and report back.

Monday, January 30, 2006

The Top Ten Lies of Entrepreneurs

Ten days ago I blogged about “The Top Ten Lies of Venture Capitalists,” as written by Silicon Valley VC guru Guy Kawasaki. So it seems only fair to direct you to his follow-up piece, “The Top Ten Lies of Entrepreneurs.”

Kawasaki says he gets pitched for funds dozens of times a year – and every pitch contains at least three or four of these lies. In fact, he says the hardest part was narrowing down the list to 10!

Below is my condensed version of his list – or you can read the original here.

1. “Our projections are conservative.” I have never seen an entrepreneur achieve even her most conservative projections. As a rule of thumb, when I see a projection, I add one year to delivery time and multiply by 0.1.

2. “(Big-name research firm) says our market will be $50 billion in 2010.” VCs don't believe these forecasts because it's the fifth one of this magnitude they've heard that day.

3. “(Big-name company) is going to sign our purchase order next week.” The funny thing is that next week the purchase order still isn't signed. Nor the week after. The decision maker gets laid off, the CEO gets fired, there's a natural disaster, whatever. No investor whose money you'd want will fall for this one.

4. “Key employees are set to join us as soon as we get funded." If it's true that key employees are ready to rock, have them call the VC after the meeting and testify to this effect.

5. “No one is doing what we're doing.” As a rule of thumb, if you have a good idea, five companies are going the same thing. If you have a great idea, 15 companies are doing it.

6. “No one can do what we're doing.” Entrepreneurs are kidding themselves if they think they have any monopoly on knowledge.

7. “Hurry, because several other venture capital firms are interested.” There are maybe 100 entrepreneurs in the world who can make this claim. The bad news: The fact that you are reading this blog means you're not one of them. Re-read the previous blog about the lies of VCs to learn how entrepreneurs hear “maybe” when VCs are saying “no.”

8. “Oracle/Microsoft/etc. is too big/dumb/slow to be a threat.” You think it's bravado, but VCs think it's stupidity.

9. “We have a proven management team.” If the entrepreneur were that proven, then he (a) probably wouldn't have to ask for money; (b) wouldn't be claiming that he's proven. A better strategy is to state that (a) you have relevant industry experience; (b) you are going to do whatever it takes to succeed; (c) you are going to surround yourself with directors and advisors who are proven; and (d) you'll step aside whenever it becomes necessary.

10. “Patents make our product defensible.” Patents are for impressing your parents. You won't have the time or money to sue anyone with a pocket deep enough to be worth suing.

Rick again: Of course, not all of these are lies. They are the optimism and enthusiasm that entrepreneurs need in order to get up every morning and run full-speed into the wall of indifference - again and again.
And thank goodness they do.

Thursday, January 26, 2006

Four simple things

My friend Donald Cooper, the Toronto-based retailer turned consultant and public speaker, had a dynamite newsletter today. Here's a condensed version of one of his articles: "4 simple things you can do, right now, to grow your business this year!"

Thing #1: Make a list of the top10% of your customers by sales volume. Call or visit them personally and thank them for their business. Ask what you can do to be more helpful and more valuable to them this year.

Thing #2: Make a list of the bottom 10% of your customers by sales volume. Call or visit them. Find out if they have potential or if you’re doing something to limit their business with you. If they simply aren’t and won’t be profitable, deal with it.

Thing #3: Make a list of your most important suppliers. Call or visit them and thank them for looking after you so well this past year. Ask if there’s anything you can do to be a better customer. Then ask if they have any thoughts on how they can be more helpful to you this year: opportunities, special terms, co-op programs.

Thing #4: Ask each of your staff to give you three to five ideas about things that you need to fix, create or stop doing in the business to serve customers more effectively, increase sales, reduce waste, increase efficiency or improve working conditions.

And they say business is getting too complicated... Donald Cooper has a way of getting to the heart of the matter.

Click here for Donald's full newsletter.
And visit his website here for lots of great articles and insights.

Six Rules for Better Presentations

It’s Planning Meeting Week at the software company on whose board I sit, so Wednesday morning I dropped in and sat through five PowerPoint presentations. Most were very well done.

Still, it was five PowerPoints in four hours. More than enough to get me thinking about Rick's 6 Rules for Better Presentations.

1. Have one main point. Find the unifying theme for all your ideas and slides, and use it as the backbone that connects and directs the information you present. Even a hint of a storyline makes your presentation easier to follow – and discourages “tuning out.”

2. Fight for attention. You have to earn an audience’s engagement. (You don't automatically get it just because they're in the room.) Start with a bang; use an arresting graphic, a strong metaphor, a challenge or a controversial quote. Don't just do this for effect – make it an integral part of your message. If you don't win people’s attention early, you’ll have trouble getting it later.

3. Provide relevant context. Get everyone in the audience up to speed, build significance and strengthen your argument by explaining what would happen (or has happened) if your message is ignored. Give us the “Before” as well as the “After.” If you're talking about the changes you are making in your department, for instance, talk first about where you are (or were before). The people who sell Tide by the boatload know that showing a clean shirt on TV is not enough – to make an impact, you first have to show the stains.

4. Encourage interaction. Find one or two opportunities to involve the audience in your presentation. Ask questions, troll for examples, seek suggestions. It offers your listeners a refreshing change of pace, and grabs attention fast. It also shows you're open to new ideas and aren’t assuming you have all the answers.

5. Tell stories. Most business presentations are full of generalities and abstractions. There's nothing wrong with saying things like “We produce mission-critical solution for enterprise-level clients” - so long as you garnish them with examples, anecdotes and testimonials that put a human face and a happy ending (or a clear lesson) on your points. Use descriptive words and active verbs. People remember images far better than they do words.

6. Be memorable. Just as you did at the outset (see Rule 2), drive your key points home. Use rhetorical flourishes, over-the-top gestures, repetition, humour, abrupt changes of pace, attention-getting graphics, or any creative technique you can imagine to ensure your ideas don't get buried in the avalanche of information your audience is taking in today.

Yes, you can get away with ignoring all of these “rules.” People do it every day. But if you want your presentation to be recalled, respected and influential – first make it memorable.

Tuesday, January 24, 2006

Election result: Barbarians at the Gates


You know Canadians are getting way unruly when they reject a lawyer as Prime Minister and bring in an economist instead.

Congratulations to Stephen Harper and his merry brand of Conservatives. Ontario and Quebec are trusting you to govern as if you have a minority. Rest assured that if you don’t, you won’t.

I’ve talked to a number of people who feel very sad about Paul Martin’s career arc. There was always a feeling that he was going to turn into someone of quality, but he never did. The man who entered public life to avenge his father’s political defeats (PM Senior ran twice for the Liberal leadership, losing to Pearson and Trudeau) has now failed even more utterly. To get the office he wanted so badly, he chose to split the Liberal party down the middle – and then he did nothing with the opportunity when he got it. Nothing to justify the faith so many people had in him, the personal effort he’d expended, or the damage he’d done to his own party.

There’s a lesson there for all of us.

And if the very act of pursuing ambition changes who you are, that may be good news for the dawning Harper era. He seemed very restrained and statesmanlike last night.

If the rest of his gang can be mature enough to hold off the witch burnings until the second term, we may get a good government out of this.

Saturday, January 21, 2006

The Challenge of China

A recent post at Fresh Inc., the blogging community of Inc. Magazine, got more than it bargained for when it addressed China’s Entrepreneurial Revival.

The writer, Carole Matthews, noted that China today has nearly 24 million small independent companies, and a recent BusinessWeek article says small/medium companies create 75% of new jobs. She says the country’s government has developed high-tech zones, science parks, and business incubators to promote business ownership, and has streamlined its business registration processes.

With China actively wooing overseas Chinese entrepreneurs to come home, Matthews ends her post by wondering whether, in the face of this unexpected entrepreneurial challenge, the U.S. is doing enough to promote entrepreneurship at home.

But her assumptions are questioned by a reader named “Tim,” whose comments should interest anyone considering doing business in China:

“All this roses and wine stuff about China is Cool, but having lived there and in Southeast Asia it isn't like people want you to believe.

“Yes, the government has opened up zones, but less than 20% of them are used. Why? Because of red tape, false funding, graft, and sucky, very old infrastructures that surround them. Most are in name only with no physical or government process improvement.

“China is and always has been made up of small entrepreneur-style businesses. It is built on the family business…

“The business failure rate in China is over 99% after 2 years. For every western or Asian [business] from outside China that starts and succeeds, there are roughly 1200 failures…

“Yes, China is a huge collection of small businesses and a big market but it is inconsistent and regulatory graft smothers it. … Don’t forget there are no contract laws and commerce laws to protect businesses like we have here.”

Dodge City wasn’t the safest place either. Yet America’s lawless frontier provided the foundation for many of its greatest business fortunes, from mining to newspapers to security and railroads. Clearly, this is all part of the ongoing global entrepreneurial revolution – and revolutions are never seen clearly until they are over.

Read the original posts here.

Click here for a short piece on China I wrote last year for PROFIT Magazine.

Friday, January 20, 2006

Another bloggin' milestone


Canadian Entrepreneur continues to grow at an increasing pace. I am delighted to note that today this blog receives its 3,000th visitor.

It took us seven months to get the first thousand. The most recent thousand took two months and 3 days.

Recently, we have been averaging 20 visitors a day, which is exciting stuff. Thanks to all who have made this a regular part of your Interweb experience.

Where did Sony go wrong?


How could Sony go wrong marketing the world’s coolest notebook computer to Canadian entrepreneurs?

1. Because they don’t understand what entrepreneurs do for fun.
2. And because they missed a subtle but golden opportunity to appeal to entrepreneurs’ vanity – and their need to be admired.

For more, check out this post over at our sister site, Selling to Small Business.

The Top Ten Lies of Venture Capitalists

Guy Kawasaki, the evangelist of Silicon Valley, is back. In his fascinating new blog, he reveals The Top 10 lies venture capitalists tell.

Guy is always trying to break down the communication barriers that separate entrepreneurs and VCs. As always, his work makes for amusing and valuable reading. Here's a condensed version.

Lie No. 1: “I liked your company, but my partners didn't.” This is a cop out, says Kawasaki: “A true believer would get it done.’

2. “If you get a lead [investor], we will follow.” In other words, once the entrepreneur doesn't need the money, the VC would be happy to give him some more.

3. “Show us some traction, and we'll invest.” The VC is saying she doesn't believe your story – but she doesn’t want to say No because she might be wrong and doesn't want to end up looking stupid.

4. “We love to co-invest with other venture capitalists.” What entrepreneurs want to hear is, “We want the whole round. We don't want any other investors.”

5. “We're investing in your team.” What the VC is saying is, “We're investing in your team as long as things are going well, but if they go bad we will fire your ass because no one is indispensable.”

6. “I have lots of bandwidth to dedicate to your company.” Counting board meetings, assume that a VC will spend no more than five to ten hours a month on your company. Deal with it. And make board meetings short!

7. “This is a vanilla term sheet.” Do you think corporate finance attorneys are paid $400/hour to push plain-vanilla term sheets? (If you insist on charaterizing term sheets as ice cream flavors, the only flavor that works is Rocky Road.) This is why you need your own $400/hour attorney.

8. “We can open up doors for you at our client companies.” Frankly, a VC might be hated by the client company. The worst thing in the world may be a referral from him.

9. “We like early-stage investing.” Venture capitalists are remarkably risk-averse, considering it's not even our money.

There is no No. 10. “I'm at a Starbucks in Hawaii writing this blog. I've been at it for ninety minutes. I don't have my charger with me. My PowerBook is out of gas.” Deal with it.
Or read the original (with the accompanying comments) here.

Wednesday, January 18, 2006

Show me the microphone!

It's time I let you know that I'll be speaking at a "Future Leaders" event in Toronto on Feb. 8. It's called an "Entrepreneurs' Forum," and I'll be speaking on "Lessons from Canada's top growth companies." There'll be war stories, best practices and road-tested tactics from some of the best companies I've met over the past year.

But that's not all! Also on the program is Manjit Minhas, founder and president of the Minhas Creek Brewing Co., an astonishingly ambitious growth company from Westerm Canada.

It'll be a fabulous one-two punch - a guy who has studied entrepreneurship up close for 20 years, and a 20-something entrepreneur who is actually making things happen.
To read more about Manjit, click here. To read more about me.... keep scrolling.

The event starts at 5 pm at the National Club, right downtown at Bay and King. For more information on this event, just click here.
See you there!

Monday, January 16, 2006

Networking at the Top

Sometimes the best marketing is done face-to-face – especially with those key, affluent individuals who hold the purse strings for major companies and customers.

In a recent issue devoted to its annual list of the 100 richest Canadians, Canadian Business magazine featured a story, Schmoozing 101, on how to network with the business elite. Here are a few highlights:

· Whether you're in an airport lounge or attending a black-tie gala, always be ready to network. If you know in advance who you might meet, find out at least three things about them. A quick Google search can help you figure out where people are from, where they work and what charities they support. You should also prepare a few questions, such as, "What are your tips for being successful?"

· Prepare a brief (seven to nine seconds) personal introduction to break the ice.

· Master small talk. Ease into conversations by finding a common interest.

· If it's necessary to talk business at a social function, provide a subtle warning to gauge its appropriateness.

· Follow up with an e-mail and a handwritten note. Know when to back off if someone's not returning calls.

· Never ignore spouses or significant others. They like to be in the conversation too – and could be influential advocates in future.

For the full story, click here.

Thursday, January 12, 2006

The new economy vs Paul Martin

Finally, the new, entrepreneurial, knowledge-based economy gets a mention in the six-week-old election campaign – and Paul Martin screws it up.

In Markham, Ont., this morning, the Liberals announced their intention to make “significant investments to support the innovation process from start to finish, from nurturing Canadian ideas, to bringing ideas to market, to supporting Canadian industry.”

Here’s the problem: a key pillar of the new economy is disgusted at the politicians’ bungling of the knowledge file. Howard Burton is executive director of the Perimeter Institute for Theoretical Physics, the leading-edge thinktank established by RIM founder Mike Lazaridis, and one of the key institutes the Liberals are now supporting.

As revealed by Maclean’s columnist Paul Wells in his blog today, Burton deliberately stayed away from the announcement.

Here’s what Burton wrote today in an e-mail written to Wells (and published in his blog):
“This morning, the Prime Minister of Canada delivered a speech explicitly promising strong financial support to my research institution for the next few years... Throughout the past year, I had imagined this moment many times: the culmination of many months of detailed discussion amongst policy experts and political representatives at both the provincial and federal level, it would be a proud, festive occasion attended by a wide spectrum of scientists, staff and Board Members: a strong endorsement of the success of our past efforts and a continued commitment to invest in our science and our researchers….

Reality, sadly, was very different. There was no coherent, long-term framework presented. There was no serious, comprehensive plan at all.… The announcement had been reduced to a mere political event - today's desperate attempt to rescue a quasi-moribund Liberal political campaign during an election that was wholly devoid of any substantive dialogue on science and research policy. And I couldn't even stomach the thought of showing up.

This is not the way that one should set meaningful policy. This is not the way that one should engage with the electorate. This is not the way that a serious country should act. …

“University officials who stood smiling on the podium with Paul Martin today, anxious for their own piece of the action, should know better. The Liberal Party of Canada should know better. We are talking about something much larger than the merits of any particular project here: we are talking about a process, about a way of developing a coherent plan of action in a highly competitive, pivotal realm that affects all Canadians. If we want to be taken seriously around the world, we'd better start acting like a serious country.”

Wow. Kudos to Burton for standing up for sanity and to process. And to Wells for uncovering the story. Read the whole sorry mess here.

Now here’s a real Canadian entrepreneur!


Yet once again we see talented Canadians selling raw, unprocessed natural resources instead of value-added products incorporating high-end manufacturing and design.

Hewers of wood, drawers of (slightly frozen) water.

I found this here.

Wednesday, January 11, 2006

Fast Growth Company Quiz

I accidentally found this quiz on a cached page at Google. It was written for PROFITguide in 2000 and taken offline sometime since then.

But it still has some interesting information, so take a minute and try the quiz. I've put the answers at the end of the post. There used to be an automated scoring page, but that's as dead as the Pets.com sock puppet.

Do you have the right stuff to run a fast-growth company? Test your mettle and pick up a few pointers from our Growth Business quiz. Questions and correct answers are derived from Secrets of Success from Canada's Fastest-Growing Companies, by Rick Spence, a PROFIT book published by John Wiley & Sons in 1997.

1. According to Spence, how many hours per week do fast-growth entrepreneurs work?
a. 30 b. 40 c. 50 d. 60

2. According to a 1994 Statistics Canada study, what is the key characteristic of successful growth firms?
a. Perseverance
b. Skill at innovation
c. Quality of management
d. Motivation of workforce
e. All of the above

3. Almost everyone knows Yogen-Fruz, the Toronto-based frozen-yogurt maker (now CoolBrands). How did the founding Serruya brothers, barely in their 20s, get started in the face of tough competition from bigger firms?
a. They had a superior product.
b. They knew the market better.
c. They tied up the best real estate.
d. They built their stores in indoor malls while a U.S.-based competitor built streetfront outlets.

4. Many of Canada's fastest-growing companies were started by entrepreneurs who at the time had:
a. Only the vaguest notion of what they were going to do
b. A $1-million line of bank credit
c. A Royal charter
d. A fishing line and a paperclip that could be bent into a hook.

5. According to Spence, how did most of these entrepreneurs evolve their business into huge successes?
a. By borrowing more than they could afford
b. By buying an existing company
c. By getting to know their customers and adapting to market needs
d. By taking night courses and management seminars
e. All of the above

6. Why did Iona Appliances president Allan Millman realize his Welland, Ont. company couldn't get away with manufacturing kitchen appliances that were "just good enough" any more?
a. Because the appliances told him so
b. Because Iona's existing products didn't offer sufficient innovation or value to crack world markets
c. Customers were complaining about appliance quality
d. Because Canada's labor costs were too high to permit manufacturing of consumer products
e. None of the above

7. So what did Millman do to rejuvenate his company?
a. Launched a world-wide search for innovative new products
b. Licensed a design for a more efficient vacuum cleaner
c. Muscled into the U.S. market
d. Launched a line of 30-minute infomercial and started selling to U.S. consumers directly
e. All of the above
(Sadly, Iona [renamed Fantom Technologies] bit the dust a few years ago. But it was a bold effort that defied long odds.)

8. "One plus one does not equal two," says Robert Murray, co-founder of fast-growth trucking firm MSM Transportation in Bolton, Ont. What did he mean?
a. Having two partners run a company jointly is a counter-productive nightmare
b. Having two people run a company jointly is a way of generating more value than either could create on their own
c. A successful fast-growth company should not try to acquire other businesses
d. You don't have to be able to add to be a successful entrepreneur
e. None of the above

9. Which of the following management tactics do Canada's top growth companies use to reward their hard-working staffs?
a. Pizza parties or a free lunch in the office to celebrate a new order or contract
b. Cash bonuses amounting to 20% of profits
c. Group activities such as ski trips and hiking days
d. Showers in the office
e. All of the above

10. One chapter of Spence's book offers an in-depth look at one growth company: Toronto-based software developer KL Group [later renamed Sitraka]. What turned out to be the theme of this chapter?
a. Growth companies don't have any fun
b. Successful leadership of a fast-growth firm requires single-minded dedication
c. Canadian companies can't compete
d. Successful leadership of a fast-growth firm is an ongoing lesson in serial delegation
e. A two-letter business name isn't as good as a three-letter name

Your correct answers are:
1: d,2: e, 3: d,4: a,5: c,6: b,7: e,8: b,9: e,10: d.

If you'd like, you can follow this link to purchase one of the last remaining copies of my book.
And keep watching this blog for news about a follow-up book that will bring growth management into the 21st century.

Tuesday, January 10, 2006

How to Cope with Catastrophe

Paul E Adams is a U.S.-based entrepreneur and former business professor who has been writing regular articles for the Canadian small-biz website, CanadaOne, almost since it started. Now he is hanging up his hat, and CanadaOne is highlighting some of his best columns.

I haven’t been a regular reader, but one of Adams’ best-of columns caught my eye. “Steps to Survival: How to Save a Sinking Business” mixes useful advice for troubled businesses with Adams’ own first-person chronicle of his 1982 descent into business failure and his long fight to turn things around. Not many authors of business advice have been through the wringer themselves, so this makes for lively reading – and excellent learning.

“All of my previous business experience and education did not prepare me for these emotions of failure,” Adams writes. “As a professor of business, I was not setting an example of successful entrepreneurship. My feelings of self-confidence and self-worth evaporated. In a year, I went from the excitement of a new business- to desperation. It was awful.”

Adams’ checklist for survival:
- Fire yourself as president – and reinvent yourself as a turnaround specialist.
- Be a Miser! Hoard every Dollar!
- Forecast your cash needs monthly.
- Start working with your creditors on new payment arrangements - before the collection calls begin.
- Collect the money that’s owed to you.
- Tap your inventory for money.
- Pump Up Your Sales Efforts.
- “Don't assume a single ad, a single article, your business card, a small sign, or a listing in the yellow pages will do it for you,” says Adams. “A sales and promotion strategy is as important as a financial strategy is to your success. It requires a credible message repeated many times.”

You can read the full story here.

Monday, January 09, 2006

Finding the right people with the write stuff

Everyone I know in business complains about how hard it is to find good salespeople.

Sure, talent is rare. But are you doing your best to make sure the sales people you hire can really do the job?

In her recent e-mail newsletter, “Something for Nothing,” Toronto sales coach Nicki Weiss offers 8 Overlooked Ways To Hire Winners. Knowing that so many sales managers despair of their staff’s written communication skills, I was particularly impressed by Nicki’s third point. It’s simple to do and oh, so powerful…

"Hand the candidate a sheet of paper, right here, right now.

"Hiring someone who seems great, then finding out that he or she doesn’t have basic writing, analytical or organizing skills, can cost a lot in extra training or in another candidate search. As part of your interview process, hand each candidate a blank sheet of paper. Ask them to hand-write why they are a sales superstar; what they would do in the first 30, 60 or 90 days on the job; and what it will take for them to be successful.

"You will see the quality of their writing, their level of skill in analyzing and problem-solving, and their ability to organize their thoughts. This information is priceless."

Not everyone has the guts to ask candidates to jump through hoops such as this one. But if you’re looking for specific skills, never take them on faith. Identify the key characteristics you’re looking for in your people, and build them into your interview/assessment process.

Otherwise, you’ll have no one to blame but yourself.

For more on coach and consultant Nicki Weiss, see http://www.saleswise.ca/

Friday, January 06, 2006

Who’s your Goal Buddy?

Motivating ourselves by ourselves can be tough. Having someone to be accountable to may be your key to goal-setting success.

Susan Ward, proprietor of About.com’s Small Business: Canada site, offers a solution: Get a goal buddy: someone to share your objectives with who will also hold your feeet to the fire.

Ward offers three reasons why goal buddies work:
* They provide motivation;
* They force accountability;
* They increase our determination.

“If you don’t have a goal buddy,” writes Ward, “it’s too easy to shelve the goal, saying, ‘I’ll work on this later.’ Having a goal buddy that we talk to regularly encourages us to make regular and steady progress.”

How do you find a Goal Buddy? Ward suggests searching your own social circle first for friends or contacts whose goals and interests are similar to yours. Online special-interest groups such as business forums may also yield helpful partners. They don’t even need to be in the same city!

To get the most from your Goal-Buddy relationship, determine how you will work together.

“Decide on how and when you’re going to regularly communicate,” says Ward. “Will you call or email each other every day? Meet for coffee somewhere once a week? By setting appointments to communicate on a regular basis, you force yourselves to work consistently towards your goals and increase your chances of achieving them.”

Rule 1, of course: Set specific goals and share them.

For more on goal buddies, click here.

Monday, January 02, 2006

Jump-start your year!

My friend Kelley Robertson, the sales trainer and author in Oakville, Ont,. hits the nail on the head today in an e-newsletter challenging us to jump-start our results this year.

He offers a three-step formula for success:

Step 1: "Review your accomplishments," says Kelley. "I believe it is crucial to pat yourself on the back for a job well done and to take some time to reflect on what you accomplished in the preceding 12 months. Far too often we focus on what we didn’t achieve instead of the victories we won."

Step 2: "Set goals for the upcoming year. Rather than leaving your results to chance, establish clear and challenging goals for yourself. Make sure they are specific, motivational, action-oriented, relevant to your situation, and time-bound."

(That's the SMART forumla, for those who don't recognize it.)

Step 3: "Discuss your goals with other people. Recent conversations with friends and business associates reminded me how effective this strategy is to re-energize our commitment. And remember to have these conversations throughout the year as a regular 'boost'."

Chasing success doesn't have to be hard - if we can be SMART about it.

Click here for more on Kelley and his work.

Sunday, January 01, 2006

A New Year's Message on Clear Communication

As you may know, I am a huge believer in clear, simple communication in business (as in life).
Your communications must state clearly what you want or intend, and the benefits that the reader/listener may thereby derive.

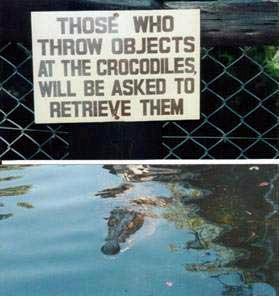
I think we have much to learn from the following sign:


Happy New Year!

Wednesday, December 28, 2005

"Business today is drowning"

“Business today is drowning in bulls--t.”

That’s the message (and opening sentence) of “Why Business People Speak Like Idiots: A Bullfighter’s Guide,” a short, breezy diatribe published this year by Brian Fugere, Chelsea Hardaway and Jon Warshawsky.

The authors, U.S.-based marketers and consultants, take aim at the jargon, clichés and thoughtless repetition that sums up most business communication today. Memos that say things like “the committee will report back with a work plan for implementing the mission-critical changes necessary to transform our company into a more agile, customer-focused enterprise” are not just contrived and dull, but inimical to the way human beings like to communicate.

“Outside of work,” say the authors, people enjoy “a fundamentally different kind of conversation – a human one, with stories and color. Informal, spontaneous, warm, funny and real.”

As a writer and marketing consultant, I agree. Too many business people hide behind bland, unimaginative, they-can’t-fire-me-for-this phraseology. It’s an excuse for not thinking, for not taking the time to see beyond the next necessary step in order to find more unique, imaginative solutions, ideas and challenges. Our dependence on jargon, I think, betrays a lack of confidence in ourselves, a lack of commitment to our projects, and a failure of imagination, which I think is essential in business.

The authors believe there’s a grim consequence to writing and saying that bore people: no one really listens anymore. Most business communication is intended to persuade people (customers, bosses, co-workers) to do something. But if nobody’s listening, nothing happens.

The authors’ goal is to restore your persuasiveness by helping you write and speak so that people will listen again. “Entire careers can be built on straight talk – precisely because it is so rare.”

What should you watch out for in your writing? Jargon, wordiness, evasiveness.

How can you gain more attention need influence? Be concise, the authors advise (in fact, their book is only 165 digest-sized pages). Use fewer words, and shorter words.

Brand your work by eschewing templated slides, phoning instead of e-mailing, writing more exciting titles or subject lines, using humour (carefully), or telling stories instead of explaining policies.

And show, don’t tell.

Tuesday, December 27, 2005

Sorry - the parking lot is full because all our staff came to work today

With Christmas over, it's time to start thinking about the New Year -- and your NewYear's resolutions.

Specifically, resolve not to make any of the mistakes made by the clowns mentioned in this article on the 9 worst business practices of 2005.

As Woody Allen once said, "Eighty percent of success is showing up."

Friday, December 23, 2005

Santa versus the Hurricanes


This comes from a blogger in Beaumont, Texas.

The Night Before Christmas
2005

Tis the night before Christmas
and all through the town
Debris of all kind is stacked in a mound.
Houses are beat up, trees are not there
The landscape is different and curiously bare.
Fences are gone and the dogs have got out
Insurance agents are nowhere about.
Mold in its grandeur is lining the walls
Inside the cabinets and all through the halls.

Moms are exhausted and daddies are spent
They're paying their house notes and now paying rent
FEMA is long gone, the Red Cross has split
Searching for new towns disasters have hit.

The children are restless as they lay in their beds
Troubled thoughts filling their heads
Can Santa find them amid all the rubble
Or will he think it's just not worth the trouble?

Then out of the night comes the sound of small hoofs
Prancing and pawing atop the blue roofs
Though Santa's landmarks were not where they'd been
The shine of the trailers guided him in
He managed somehow to deliver the toys
To all the deserving good girls and boys

And they heard him exclaim as he drove out of sight
"It takes more than Rita to mess up this night!"

Merry Christmas to all.

Fitness Tips for You and Your Business

I have quoted Jim Estill before, the entrepreneurial CEO of Synnex Canada, but he just keeps turning out good stuff at his blog on Time Leadership.

A runner and fitness buff, Jim mused recently on the parallels between exercise and business. Here’s a condensed version of his thoughts.

* Even if you think you are in shape, you will do some activity that makes you sore. The same is true in business. Regardless of how skilled you are, there will be new situations that will challenge you.

* Muscles adapt to the exercise routine so it becomes easier, but you do not get as good a workout. The same is true in business. By always taking the same challenges, you will get good at them, but you can also become stale. So mix it up a bit to grow.

* Overcoming challenge, procrastination and external events happens in both exercise and business. Devise systems to get re-energized and deal with the inevitable challenges.

* Small wins build confidence and lead to bigger wins. So just get started.

Great advice from a man who started a business from the trunk of his car and now runs a $1-billion company. Read Jim’s entire post here.

Thursday, December 22, 2005

With sprinkles on top


If you didn't get my e-Christmas card this week, here's a copy. And please accept my best wishes for a visionary, self-improving and client-focussed holiday season.


For more holiday greetings (from some over-achieving Hungarians, I believe), click here. And turn up the sound.
(Thanks to my Uncle Jack in Minneapolis for this fun link.)

Tuesday, December 20, 2005

So the Liberals knew all the time they should do this...

On Monday (Dec. 19), election candidate Paul Martin announced that the Liberals would increase the lifetime capital gains tax exemption for small businesses (and farmers) by 50%.

Last summer, I talked to an official at the Industry Dept's small business braintrust about this long-overdue move. (It's a good partial remedy to the looming sucession crisis that I've written about.) I was assured this move was not being considered. Not a priority. Not on the radar.

Suddenly, Paul Martin thinks it's a good idea. Hard to believe that he's been Prime Minister for two years, or that his party has been in power for more than 12 years.

Maybe if the Liberals didn't wait for elections to do the right thing, they wouldn't be facing an election now.

(From the Liberals' official press release, the fine print: “There’s nothing small about the role small business plays in the creation of jobs and growth in Canada’s economy,” the Prime Minister said. “Raising the lifetime capital gains exemption to $750,000 from $500,000 will allow small-business people and farmers to keep more of the profit from the sale and transfer of their businesses to a new generation.”)

(And then there's the appeal to your heartstrings: "A Liberal government will continue to create an economic environment that helps small businesses continue to thrive – not just as the engine of economic growth, but as the place where Canadians’ dreams come true.")

Reduce taxes, Paul. Lower interest rates. Dump the GST. Then maybe we'll believe you.

Andrew Coyne has a sense of humor

Excerpt from Andrew's blog, Dec. 14:

"... But what's common to all the polls are the huge numbers saying they want a change in government. The Strategic Counsel found 58% answering the "time for a change" question in the affirmative, a number which must make the Grits' blood run cold.

"If ever the voters start to make the connection between changing the government and voting for the opposition, they'll be in real trouble."

Read more here.

(Not being very political, other than thinking that most politicians should be sent to witless relocation programs, I will not often be blogging about the X-mas L-ection. But this was too good not to share.)

Thursday, December 15, 2005

Special Announcement with a tinge of irony

Early in my career as editor of PROFIT Magazine, I set aside some budget money for a Freelance Writer of the Year award. It was a way of honoring the contributions of the freelance writers who produce most of the content for most Canadian magazines, and recognizing outstanding work.

Well, the editors at PROFIT surprised me today by letting me know I had won the award this year, and that a little cheque would be coming my way.

(Now, of course, I wish we'd sprung for a trophy, too.)

They say I won for two entries: a story on the looming succession crisis, and the Spin Master Toys profile in the current issue, which I blogged about just recently.

Looking for some award-winning reading? You can read the Succession story here, or click here for Spin Master.

Wednesday, December 14, 2005

Focus, people, focus!

Focus, people, focus!

Already this week I’ve had two conversations with entrepreneurs about marketing/public relations, and I had to spend way too long figuring out who their market is. They are wonderfully bright and intelligent business people, but they were sadly inarticulate when it came to defining their marketplace and the needs of their prospects.

And they’re not alone.

In my experience, the evolution of a business goes like this: it starts with a specific product or service and a small group of clients, many of them previously known to the business owner and motivated to work with him or her.

Over time, the product develops and evolves, and new customers climb aboard – friends and acquaintances of the owners and their staff, local purchasers, and others who intuitively understand the product or service. This process can take years, and the company can be reasonably successful.

But there comes a time when companies need more. And they suddenly discover that they don’t know who their customer is. They don’t have a marketing strategy, or even a plan, and they don’t really understand their value proposition beyond the sale pitch they may personally make every day. In other words, there’s been no separation of the owner from the business – and no articulation of the company’s value-add, its benefit statements or its marketing vision.

Yes, marketing or communication consultants can help. But before you seek them out, make the most of your time together by thinking through questions such as these:

* Who is/are my target market(s)?
* Is this really the best and most valuable market I could be appealing to?
* What is my plan for reaching my target market(s)?
* What is the value of a new customer? How much can I afford to (or do I want to) spend on marketing?
* What do clients and prospects want from me? What problems does my company solve?
* What do existing clients say about my company, product or service? Do I have testimonials in their words that help me understand what my product/solution means to them?
* If not, can I ask them for testimonials, and learn from those?
* Have I surveyed my customers to find out what they like about us, what they don’t like, and how we can serve them better?
* What media do my prospects read/watch/consume? How do they like to be contacted?

Knowing all this in advance will not only save you time (and money) in developing your marketing messages and plans. It will also give you a big advantage over most of your competitors.

Tuesday, December 13, 2005

The Growing Clout of Small Business

There are encouraging signs that entrepreneurship is on the march again.

In good times, everyone gets excited about working on Bay Street or going to work for big companies. But when shocks appear – and this summer’s oil price spike was an 8.8 on the Richter scale of business confidence – people get nervous about the prospects for big, dumb corporations, and they look again to the opportunity and security afforded by small business.

A few weeks ago, RBC Financial produced a survey that found more than a million Canadians are thinking of starting up a new business.

At the same time, a Scotiabank survey found 90% of Canadian entrepreneurs believe their business will perform as well or better one year from now than it does today. "It's encouraging to the business community on the whole that small business owners are generally enthusiastic about the potential for increased earnings," noted Diane Giard, Scotia’s VP of small business banking.

A CIBC World Markets study estimates 80,000 Canadians will become small business owners this year, swelling the national total to 2.5 million. Even better, says CIBC, "nearly one in four Canadians say they will be self-employed at some point in the next five years."

And today, I got an e-newsletter from VISA promoting discounts for small business (itself an indicator of the market’s clout) – and several articles geared to entrepreneurs (altho’ they’re a bit dull). In one story, writer Chuck Davies quotes CFIB economist Ted Mallett musing about the positive forces behind today's startups.

"We know that two thirds to three quarters of people who enter self-employment do so for positive reasons, they go in with their eyes wide open. It's part of their plan,” says Mallett. “The rest do it because they're forced into it, either because they haven't been able to find paid employment opportunities or because they've been laid off or downsized."

Mallett also notes suppliers’ growing interest in the small-business market. "Banks and financial institutions have realized that small business owners are a very profitable segment for them. A startup may not have much to go on, but the fact that the person starting it up is 45 years old, has finished a mid-level career, has a nice amount of equity in their home, is driven and has a good credit record – this person is going to be very profitable for a bank if treated right."

Mallett sees other suppliers joining the trend. In particular, providers of information technology are starting to realize “they've got to target a class of business that's considerably smaller than the ones they've been used to dealing with," he says. "That means their solutions and their pricing models have to be different."

In fact, yesterday the Globe ran an article saying more telecom firms are viewing small business as a market segment worthy of its own products and dedicated strategies. This isn’t new (anyone remember BellZinc.com?) – but it seems a broader initiative than we’ve seen before.

So the next time you buy from a supplier, make sure they speak your language. Demand service levels and pricing structures that make sense for you, not just for IBM.

If entrepreneurs are to be truly recognized as the backbone of this country, we should show more backbone.